


Hurricane Deductibles in Hawaii: How They Work and What to Check
A percentage hurricane deductible can be the biggest number on your claim. Here is how it is triggered, calculated and reviewed in appraisal.
Independent appraisal · Oahu to Kauai
Your insurer agreed the damage is covered, but the payment won’t rebuild it. Hawaii Insurance Appraiser prices the loss line by line — island freight, general excise tax and local labor included — and carries it through the appraisal process written into your policy.
The short version
Most underpaid island claims aren’t denials. They’re estimates with a missing roof plane, a condo ceiling below that nobody opened, freight priced like the mainland or general excise tax left off the bottom line. A Hawaii Insurance Appraiser exists for the gap between “we’ll cover it” and a check that actually rebuilds.
When either side invokes the appraisal clause, you name an appraiser, the insurer names one, and the two choose an umpire. Hawaii Insurance Appraiser can be the appraiser you name — or review the numbers first so you know whether a demand is worth making.
Specialties
Hawaii Insurance Appraiser handles hurricane, Kona-storm, wildfire, volcanic and everyday water and fire claims — for single-family homes, condominium associations and commercial buildings.
01Your appointed appraiser once either side invokes the appraisal provision in your Hawaii property policy.
Learn more 02
Appraisal support for single-family homes, ohana units and plantation-style houses when the claim number falls short.
Learn more 03
Appraisal for AOAO master-policy claims, HOA communities, unit owners and commercial buildings across the islands.
Learn more 04
Roof claim appraisal for metal, shingle and tile roofs damaged by wind, wind-driven rain or rare Hawaii hail.
Learn more 05
Appraisal for Kona low, trade-wind and downslope gust damage, plus rare waterspout or tornado losses on the islands.
Learn more 06
Hurricane claim appraisal for Hawaii homes and buildings, including deductible math, roof loss and wind-driven rain.
Learn more 07
Appraisal for plumbing leaks, condo stack pipe failures and wind-driven rain damage in Hawaii homes and units.
Learn more 08
Appraisal for structure fires, kitchen fires and smoke or soot damage to Hawaii homes, condos and businesses.
Learn more 09
Appraisal for Hawaii wildfire losses – total losses, smoke and ash, debris removal, ALE and rising rebuild costs.
Learn more 10
Appraisal for volcanic ash, vog corrosion and lava losses on the Big Island, including HPIA-insured homes.
Learn more 11
A line-by-line review of your insurer’s estimate to find missing scope, low pricing, GET and freight errors.
Learn more 12
Neutral umpire services for property insurance appraisals on every Hawaiian island, for homes, condos and businesses.
Learn moreIsland by island
A Hawaii Insurance Appraiser has to know how vog shows up on a Kona metal roof, how a stack-pipe leak travels through a Waikiki tower and what it costs to rebuild on Molokai.
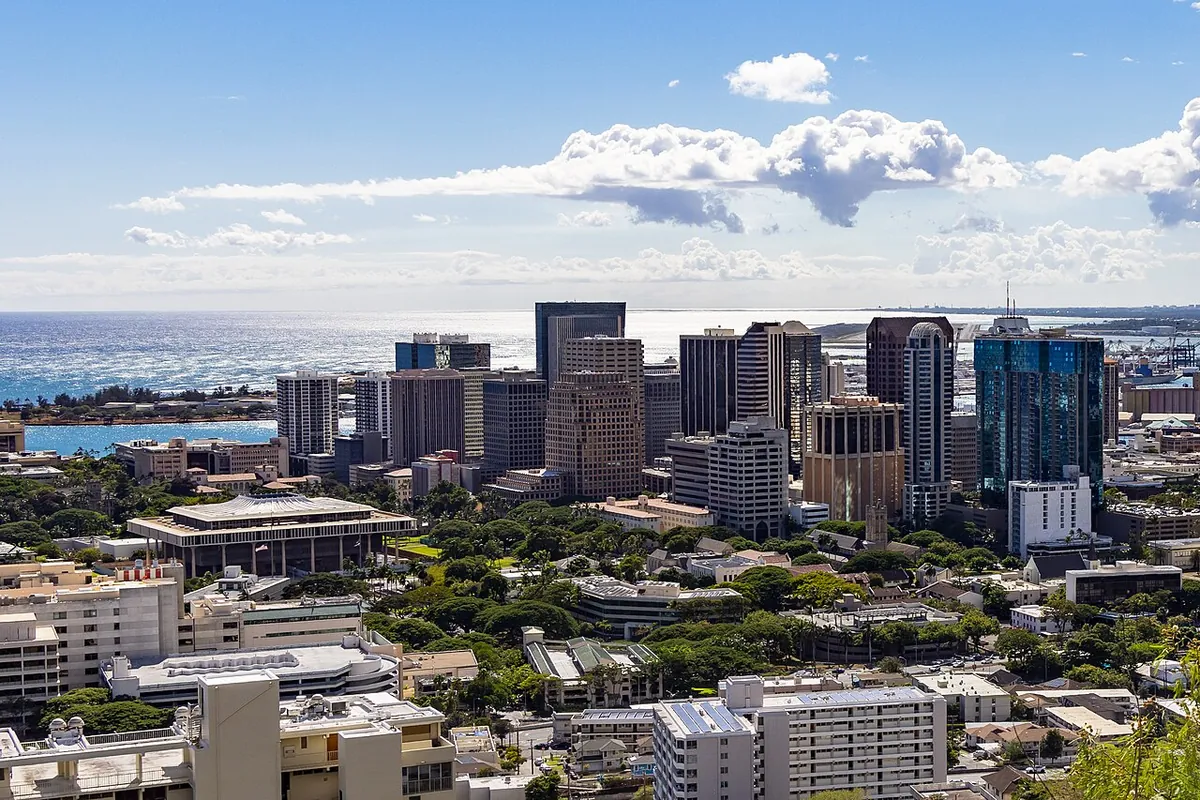
Most of the state’s people — and most of its high-rise condos — live on Oahu. Water losses that travel between units, roof damage from Kona-storm winds and flash flooding on the windward side make up a large share of disputed files, alongside leeward brush fires near Waianae and Makakilo.
Communities: Honolulu, Kailua, Kaneohe, Pearl City, Aiea, Kapolei, Ewa Beach, Mililani, Wahiawa
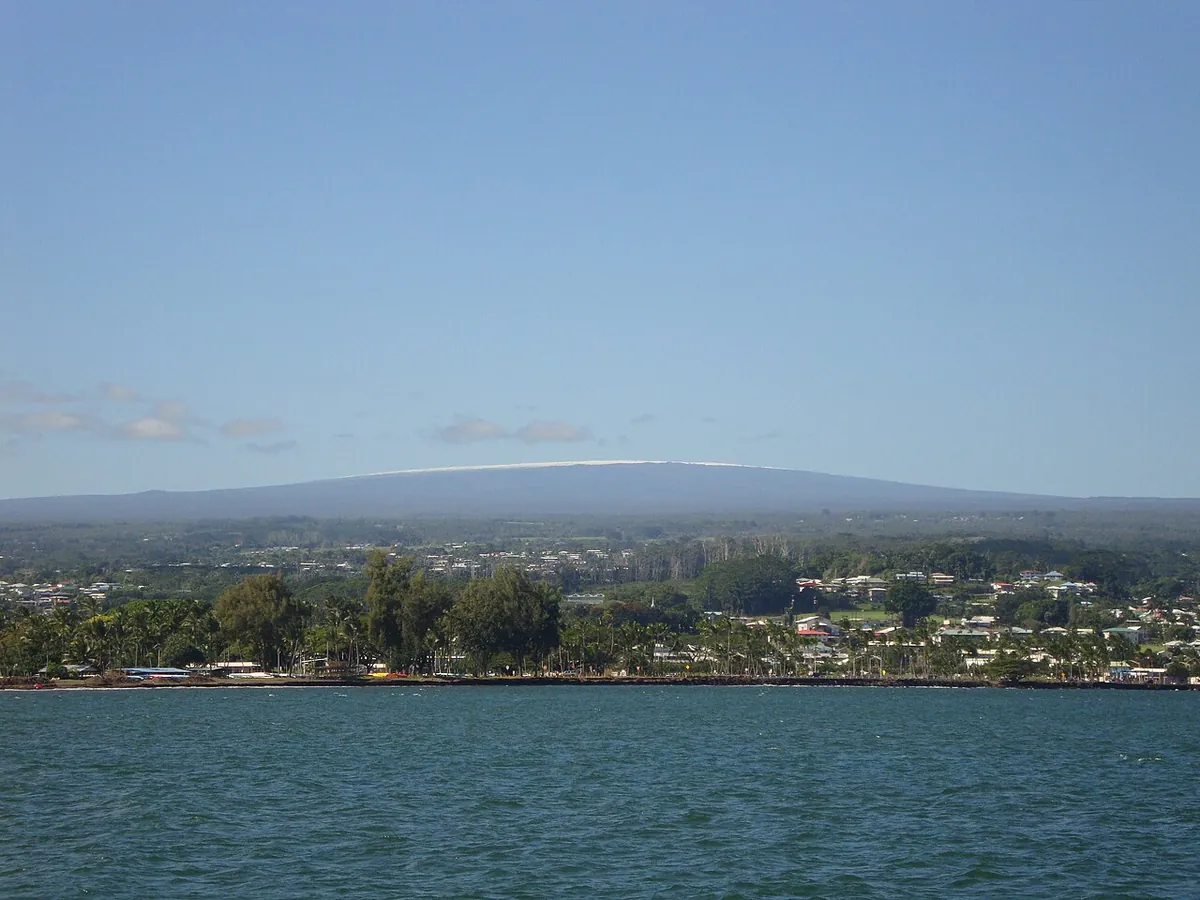
The Big Island packs rain forest, ranchland and active volcanoes into one county. Hurricane Lane’s rainfall in 2018 hit the Hilo side hard the same year Kilauea’s eruption took homes in lower Puna, and vog keeps metal roofs and fixtures on the Kona side under constant attack.
Communities: Hilo, Kailua-Kona, Pahoa, Waimea, Volcano, Honokaa, Kau
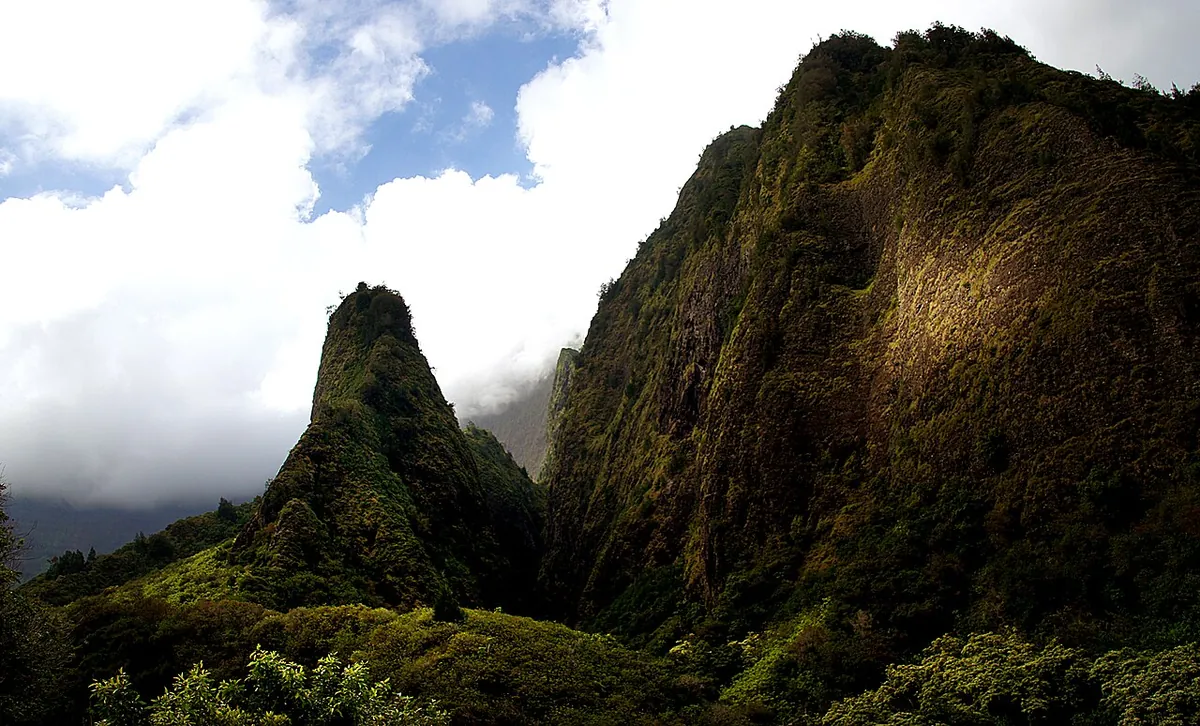
Since August 2023, wildfire has defined Maui claims: total losses in Lahaina, partial losses and smoke in Upcountry, and long arguments about rebuilding costs as labor and materials stretch thin. Kona storms and trade-wind gusts add roof and water claims across Central and South Maui.
Communities: Kahului, Wailuku, Kihei, Wailea, Lahaina, Napili, Kula, Pukalani, Makawao
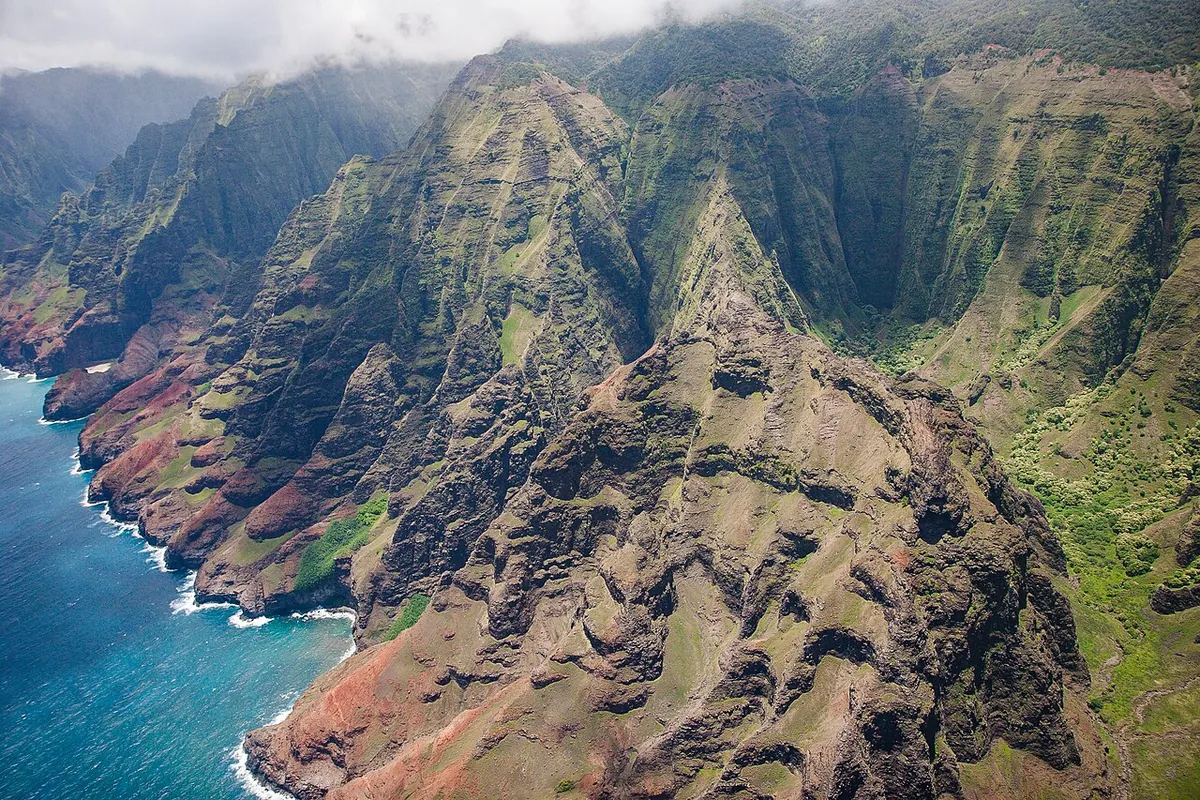
Kauai carries the memory of Iwa in 1982 and Iniki in 1992, and the 2018 north shore floods showed how fast rainfall can overwhelm roads and homes. Hurricane deductibles, wind-driven rain and the cost of shipping materials to the Garden Isle shape many disputes.
Communities: Lihue, Kapaa, Wailua, Koloa, Poipu, Princeville, Hanalei, Waimea
Small communities mean few local contractors and long lead times. Estimates for Molokai and Lanai need realistic freight, barge schedules and travel for crews — items carrier estimates sometimes price as if the home were in town on Oahu.
Communities: Kaunakakai, Maunaloa, Kalaupapa, Lanai City
Two-number gap check
Type in the carrier’s estimate and your contractor’s. A large gap is worth a conversation with a Hawaii Insurance Appraiser; a small one may close faster with a documented supplement.
The full claim gap & fee estimator adds appraiser fees, inter-island travel and the umpire share so you can see a realistic net.
Browse all seven toolsHow it works
The appraisal clause turns an open-ended argument into a defined process with a binding result. This is how Hawaii Insurance Appraiser moves a file from first call to award.
We read the policy, the carrier’s estimate and your photos, then say plainly whether appraisal fits.
Our own inspection, measurements and line-item estimate priced for your island — freight and GET included.
Appraisal is invoked in writing and you name Hawaii Insurance Appraiser as your appraiser.
We negotiate line by line with the carrier’s appraiser; most disputes narrow here.
Anything left goes to a neutral umpire. Two signatures set the amount of loss.
The record
Hurricane deductibles, lava-zone coverage and condo master-policy terms all trace back to events like these. A Hawaii Insurance Appraiser reads every estimate with this history in mind.
A direct strike on Kauai, years before most current policy forms existed.
Late-season hurricane that battered Kauai and leeward Oahu with wind and surf.
The most destructive hurricane in island history; it reshaped how hurricane coverage is sold here.
Kauai’s north shore set a U.S. 24-hour rainfall record during the April storms.
Lava from the lower East Rift Zone covered neighborhoods in Puna, including Leilani Estates.
Extreme rainfall on the Hilo side plus wind-driven fires on Maui and Oahu.
Fires in Lahaina and Upcountry produced total losses, smoke claims and long rebuild disputes.
Free & private
Seven calculators and planners built by Hawaii Insurance Appraiser from real appraisal work. Nothing you type is stored or sent anywhere.
CalculatorCompare the two estimates, test where an award might land and subtract fees, travel and half the umpire.
Open the toolCalculatorList damaged items with age and life to estimate the first ACV check, the holdback and the total after repairs.
Open the tool Calculator
Turn a footprint into true roof squares for shingle or metal roofs, then check the carrier’s measurements.
Open the toolCalculatorConvert a percentage hurricane deductible into dollars and compare what a storm claim would actually pay.
Open the tool Planner
Map notice, proof-of-loss, holdback and suit-limitation dates from your date of loss, then export them.
Open the toolChecklistAnswer 12 yes/no questions to score your file and get a to-do list before anyone invokes appraisal.
Open the toolSee all claim tools, including the condo deductible calculator
Where we work
Hawaii Insurance Appraiser takes claims in all five counties. These pages cover the places our files come from most often, with local housing and storm history.
Honest triage
Appraisal is a precise tool. Hawaii Insurance Appraiser will point you elsewhere when another route serves you better.
Questions
Straight answers from Hawaii Insurance Appraiser about how appraisal works, what it costs and when it’s the wrong move.
When you and your insurer agree a loss is covered but disagree on the cost, an appraiser values the damage independently. As your appointed appraiser we inspect, build a line-item estimate, work with the carrier’s appraiser and, if needed, present unresolved items to a neutral umpire.
No. A public adjuster handles and negotiates the whole claim. An appraiser works inside the policy’s appraisal clause on one question — the amount of loss. We don’t negotiate outside appraisal and we don’t give legal advice.
Yes. We take claims on Oahu, Hawaii Island, Maui, Kauai, Molokai and Lanai, and we’re upfront about any travel costs before work begins.
Often, yes. Association master policies usually contain an appraisal clause, and the amount of a building loss affects every owner’s deductible assessment. Unit owners may also have a separate HO-6 dispute.
Appraisal sets the amount of a covered loss; it doesn’t decide coverage. For a denial, talk to a Hawaii attorney first. We’ll tell you on the first call if your situation needs one.
Each side pays its own appraiser and usually half of the umpire. Our fee is put in writing before any work starts, and the first conversation is free.
Guides
Practical reading on hurricane deductibles, condo master policies, wildfire smoke, salt-air corrosion and island pricing.
A percentage hurricane deductible can be the biggest number on your claim. Here is how it is triggered, calculated and reviewed in appraisal.
When a stack pipe bursts or a storm hits a tower, the AOAO’s master policy and your HO-6 each pay part. Here is how to sort it out.
Smoke and soot can reach homes the flames never touched. Here is how to document wildfire smoke damage so the claim reflects what is really there.
Before you sign a release
A short review now can keep you from accepting a settlement that won’t cover the rebuild.
Start here
Tell us what happened and what the carrier offered. We’ll review it and give you a straight answer on whether appraisal is worth pursuing — no pressure, no obligation.